


In Ontario, how do I make a home insurance claim when pipes freeze and burst after a winter power outage or ice storm?
Swipe for the 1 minute answer
- 01Shut the main valve. No open flame on pipes
- 02Water near power? Wait for the utility to cut it
- 03Once water settles, shoot wide to close
- 04Open a claim the same day, note the number
- 05Start extraction and drying, keep every invoice
- 06Ask your insurer before tossing anything
Insurers usually ask for a proof of loss form, commonly within 30 days. Check your policy and your insurer.
$9,168.49 emergency work plus $18,230.30 rebuild, minus a $2,000 deductible. Get them estimated separately and keep the paperwork apart.
You get little back and a claim goes on your record. Yifei works out that number with clients before they make the call.
- 01Fix it fast and find the cause
- 02Replace a soaked water heater control board
- 03After big storms, adjusters get backed up
- 01Leave the heat on, have someone check in
- 02Or drain the plumbing
- 03Read your policy's vacancy rules first
Tell Yifei what happened and he'll tell you straight what to do.
Ask YifeiShut off the main water valve, take photos and video of the water and everything it damaged, then call your insurer or broker the same day to open a claim and write down the claim number. Many home policies cover sudden water damage from a burst pipe, after the deductible. If the house was left empty in winter without the plumbing drained or anyone checking on it, freeze damage may not be covered, so your policy wording is what counts.
What to do on day one
- Shut the main water valve. Don't use an open flame to thaw a frozen pipe; if you're unsure, call a plumber.
- If water has reached the electrical panel, outlets or furnace, stay out of the basement until the local utility has cut the power, then have a licensed electrical contractor check it.
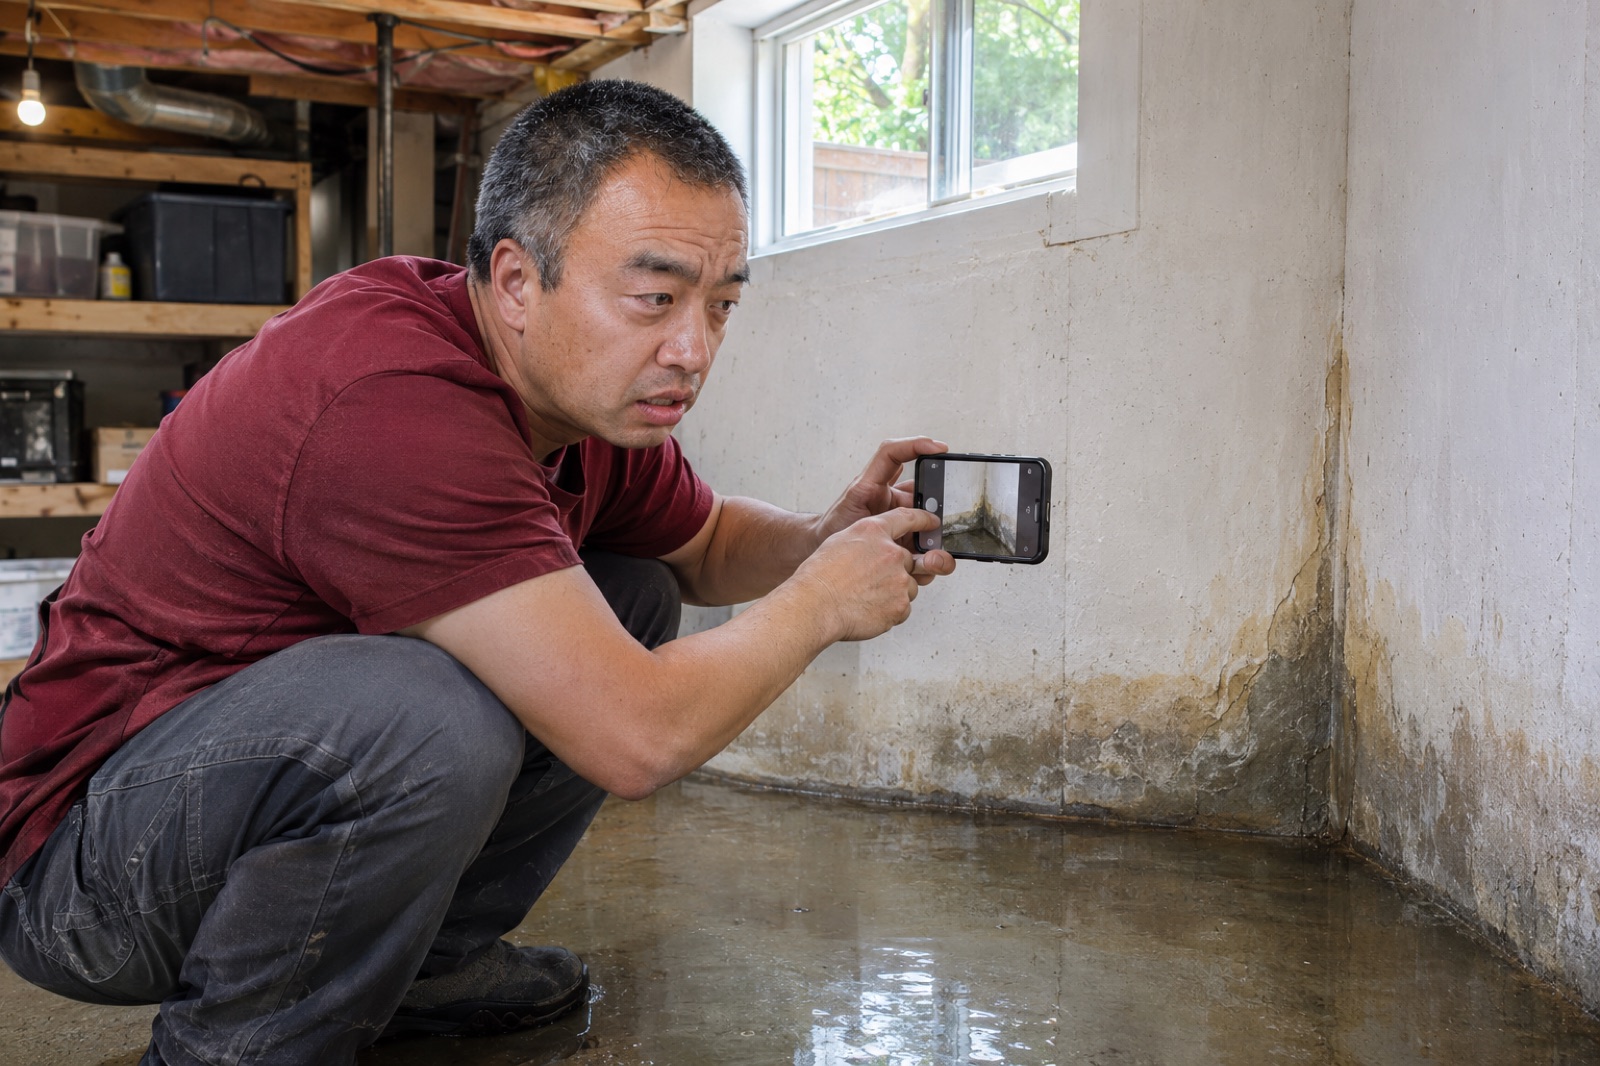
- Photograph and video everything. Yifei's approach: once the water level settles, shoot from wide to close, covering the water line, walls, floors and damaged furniture and appliances, before any cleanup.
- Open the claim and get a claim number. When the adjuster calls, give that number first. Insurers usually also ask for a proof of loss form, commonly due within 30 days; check your policy and your insurer.
- Limit the damage. Water extraction and drying can start right away; keep every invoice. Photograph items, check with your insurer before throwing anything out, and keep large items for the adjuster.
- If the house is rented, the tenant's own belongings go through the tenant's insurance.
Three things decide what you get back
For a small loss, do the math first. If the repair is $1,500 and the deductible is $1,000, you get little back and still have a claim on your record. Yifei works that number out with clients before they pick up the phone.
What Yifei has seen
On one water claim Yifei handled in 2024, the insurer approved two estimates: $9,168.49 for emergency work and $18,230.30 for rebuilding, $27,398.79 in total. After the $2,000 deductible, the cheque was $25,398.79, and the owner paid the deductible to the contractor once repairs were done. Get emergency work and rebuilding estimated separately, and keep the paperwork separate.
After a widespread event, adjusters get backed up. Yifei has seen insurers short-staffed enough to bring adjusters in from other provinces. A slow adjuster isn't the owner stalling; keep photos, receipts and call notes while you wait.
Two more of Yifei's rules:
- Fix it right away and find the cause. If it floods again a few months later and you claim again, premiums can jump sharply even if you're not dropped.
- If the control board under the water heater got wet, it's likely to give trouble. Replace it as part of the claim; if it dies on its own later, insurance probably won't cover it.
A claim doesn't always raise the premium. Yifei saw one house where the previous owner had lived for many years without a problem; a small corner leak was paid out and the premium stayed the same.
Before you travel this winter
- Leave the heat on and have someone check the house every few days, or drain the plumbing, and read your policy's rules for unoccupied homes.
- A house that's been empty for a while needs someone watching the pipes and roof.
- Drain outdoor taps before the freeze. See What winter home maintenance does a house in Toronto or Niagara actually need?
Frequently asked questions
Does insurance pay if pipes burst after a power outage?
Many policies cover sudden pipe bursts, but it depends on whether the home was occupied or being checked, and on any vacancy clause. Read the policy wording and ask your broker.
The adjuster hasn't come. Can I start repairs?
Damage control like extraction and drying can start now, and your policy expects you to limit further damage; keep photos and receipts. Hold off on opening walls or replacing floors until the adjuster has seen it or the insurer approves in writing.
Does one claim raise my premium?
Not always. Yifei has seen a small claim paid with no increase, but a second claim for the same cause soon after often costs you.
Want advice for your own situation?
Your policy wording, whether the home was occupied and where the water came from all change the answer. Tell me your situation and I'll tell you straight what to do. Yifei (RE/MAX), efay.ai.
Sources
- Insurance Bureau of Canada, How to file a home insurance claim: https://www.ibc.ca/insurance-basics/home/how-to-file-a-home-insurance-claim
- Insurance Bureau of Canada, Water damage and flood protection: https://www.ibc.ca/stay-protected/protect-your-property/flood-and-water
- Government of Canada, Power outages, how to prepare: https://www.canada.ca/en/services/policing/emergencies/preparedness/get-prepared/hazards-emergencies/power-outages/how-prepare.html
- Electrical Safety Authority (Ontario), flooding and electrical hazards: https://esasafe.com/newsroom-2025/electrical-safety-authority-warns-of-electrical-hazards-posed-by-expected-flooding/